VA Loan Credit Score Requirements in San Antonio (2026)
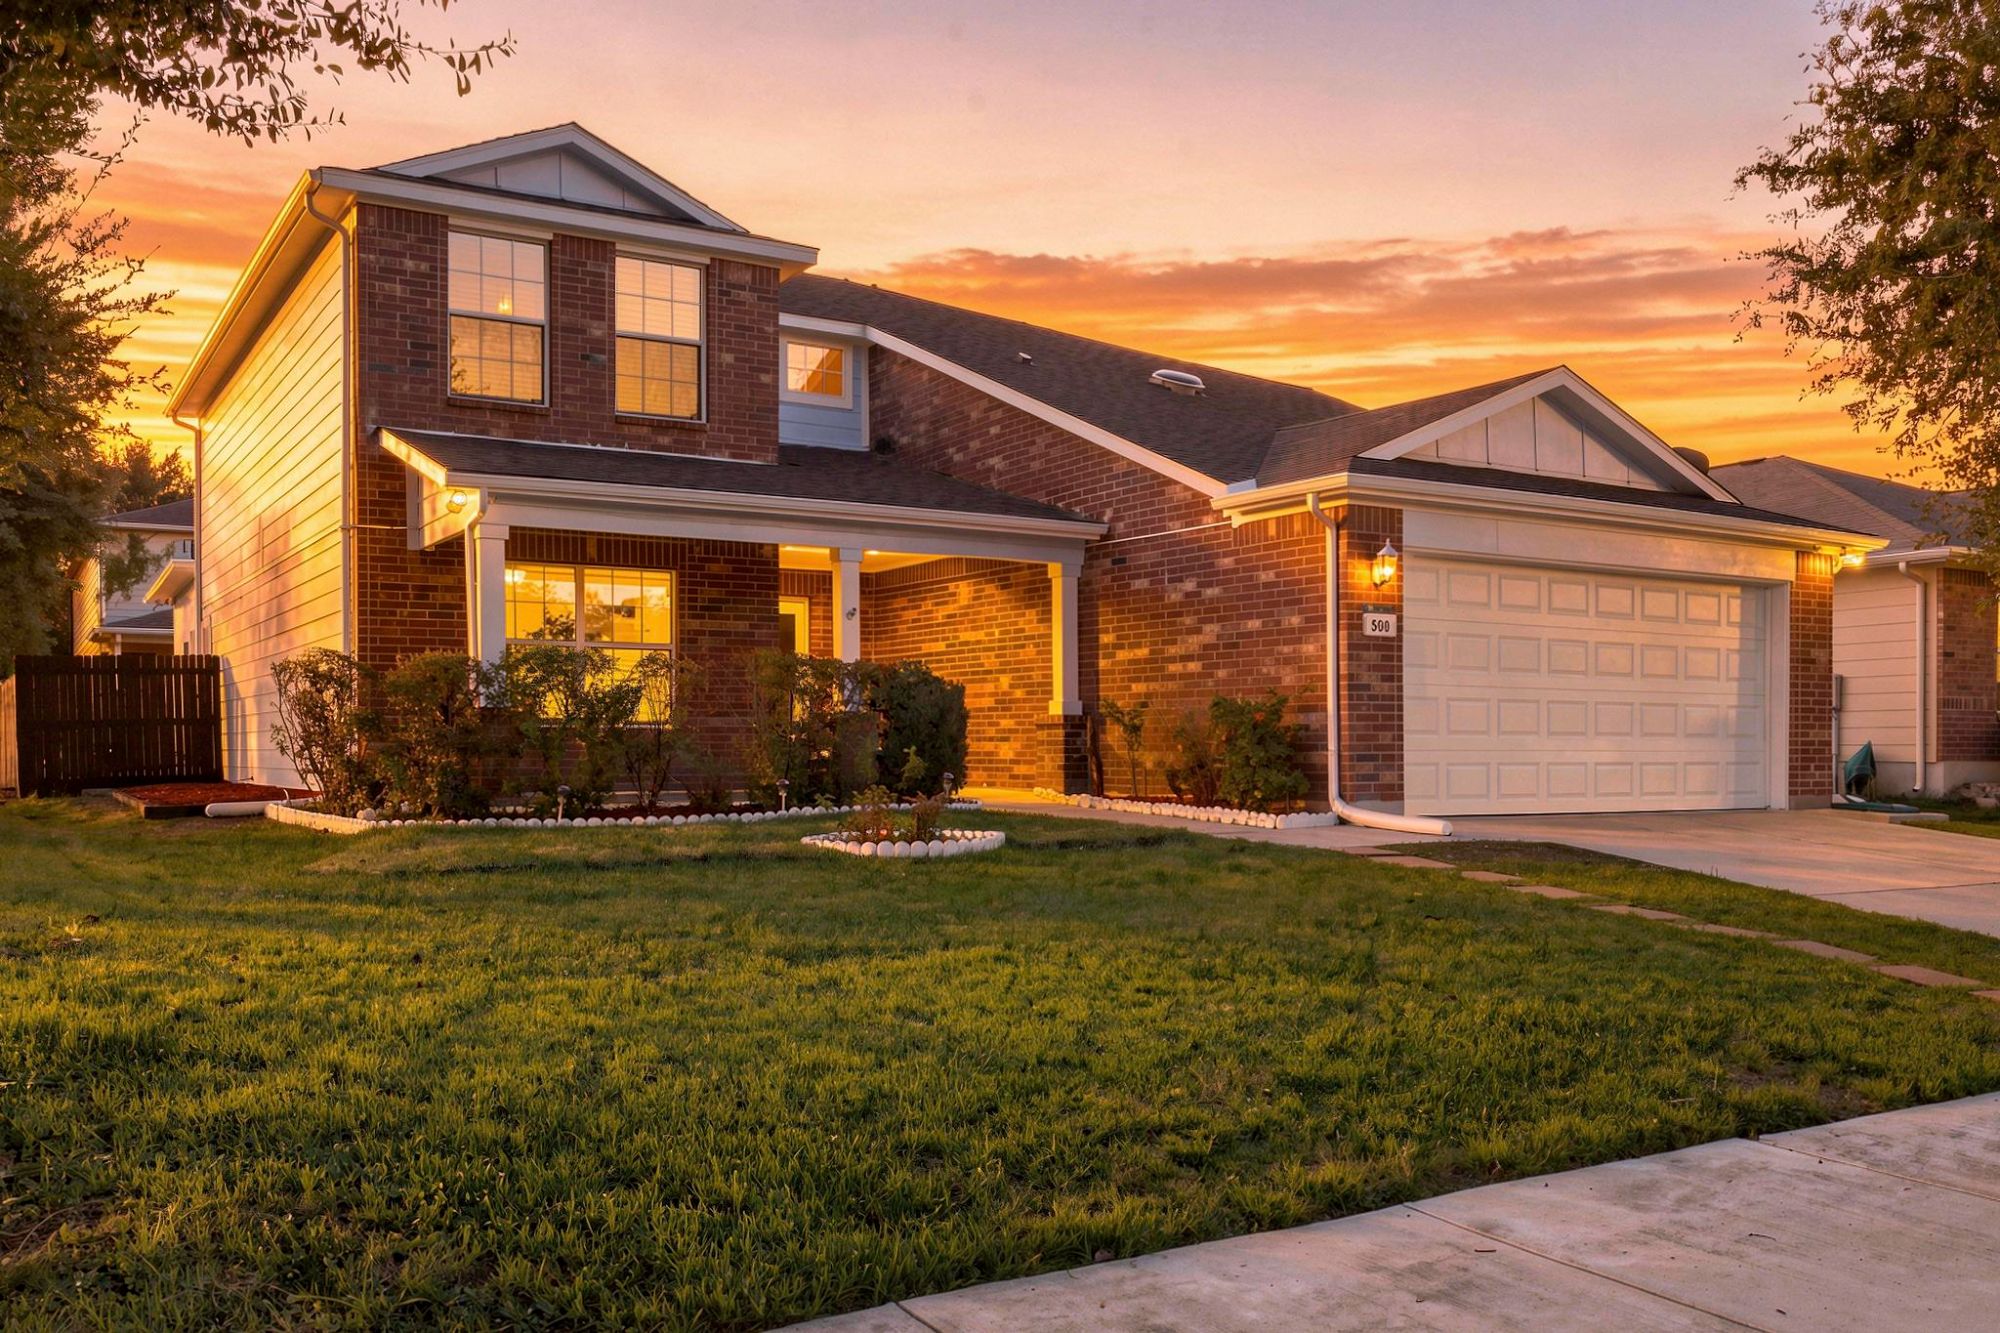
672 Planters Pass, Schertz, TX. Photo: Sharp Realty Group.
Your orders to Joint Base San Antonio (JBSA) are in hand, the house-hunting trip is booked, and the first lender you call says your credit score sits 14 points below its cutoff for a loan backed by the U.S. Department of Veterans Affairs (VA). Now you are wondering whether the zero-down benefit you earned is off the table before you have toured a single home.
That moment is where many buyers stall, and it is why VA loan credit score requirements cause so much confusion during a permanent change of station (PCS) move. One lender's number is rarely the whole story. I am Anthony Sharp, a U.S. Air Force veteran and REALTOR® with Sharp Realty Group in Cibolo, and I have used the VA home loan benefit myself. Before you sit down with a partner lender for VA loans, it helps to know how your score gets read and what you can still change.
The good news is that a low score is usually a starting point. Your credit file has other levers, from the income you have left each month to an error you can still correct, and for buyers looking near Randolph Air Force Base in Schertz, Cibolo, or Universal City, those levers can decide whether you close on your timeline.
Key Takeaways
- The VA sets no minimum credit score. The 620 floor many lenders use is their own policy and varies by lender, so one no is not the final word.
- Your score shapes your rate as well as your approval, and on a $389,900 Schertz home, a half-point rate gap can add about $136 a month, depending on your rate.
- A past bankruptcy or foreclosure is not an automatic no under VA rules, though its timing and cause both matter.
- Pulling reports early, keeping card balances low, and pausing new credit until closing can protect or lift your score before a PCS purchase.
VA Loan Credit Score Rules Versus Lender Overlays
Most of the confusion comes from two sets of rules running at once, one from the federal program and one from the company funding your loan. Knowing which one you are hearing changes how you respond to a denial:
VA Credit Standards
The VA does not publish a minimum credit score for its home loan program. Under the VA purchase loan guidelines, you need to clear a credit and income review from both the VA and your lender, hold a Certificate of Eligibility, and live in the home you buy. VA underwriting rules center on whether you are a satisfactory credit risk and whether your income can carry the new payment, so your payment history and the money left over each month can matter as much as the score itself. These standards reflect current VA rules, which the VA can update at any time.
Lender Credit Overlays
The VA guarantees only part of each loan, generally up to 25% on loans above $144,000 under current entitlement rules, and your lender still has to approve you. To manage the rest of that risk, many lenders set their own minimum score, known as an overlay. Those minimums vary from company to company, which is how one lender can turn you away at 610 while another moves forward at the same number.
When a lender turns you down over a score, the decision comes from its own policy, and another lender may see the same file differently. It is fair to ask whether a floor is a program requirement or an internal one.
Common Score Floors
Many VA lenders look for a score of at least 620, while some will work with borrowers whose scores sit in the 500s.
Those policies can change without notice, so treat any number you read online, including these, as a snapshot and confirm the current floor with your lender.
Lender Scoring Models
The score in your banking app may not match what a mortgage lender sees. Current VA rules require lenders to use a merged credit report that draws on all three bureaus, so a mistake or late payment on any one of your Equifax, Experian, or TransUnion files can show up.
For decades, loans sold to Fannie Mae and Freddie Mac relied on Classic FICO scores, and many lenders still use them. VantageScore has stated that the VA accepts loans underwritten with its VantageScore 4.0 model, but each lender picks its own model, and the models allowed for mortgages can shift as agencies and lenders update their policies, so ask yours before you plan around a number.
How Your Credit Score Shapes a VA Loan Near JBSA
Clearing a lender's minimum gets your file in the door. From there, your score keeps shaping the loan, and a few parts of the application can soften its impact:
Highlighting Compensating Factors
When part of a file looks weak, VA rules let underwriters weigh compensating factors, the strengths that balance out the soft spot. The examples VA lists include the following.
- Excellent long-term credit and conservative use of consumer credit.
- Minimal consumer debt.
- Long-term employment.
- Significant liquid assets.
- Military benefits.
- High residual income or a low debt-to-income ratio.
VA rules also say meeting the income tests does not guarantee approval, and missing one does not automatically rule you out. How much weight each factor carries is up to the underwriter and can vary by lender, so give your lender the full picture early, especially when your PCS window is short.
Comparing Rate Quotes
Your score also affects what you pay. Your lender, not the VA, sets your interest rate and any discount points, and your credit score is one of the factors behind that price. The Freddie Mac 30-year fixed average was 7.28% as of October 1, 2026, up from 7.03% a week earlier. That survey reflects conventional loans for borrowers with excellent credit and 20% down, so your VA quote may land above or below it. Rates change weekly and every lender prices loans differently.
To see what a half-point gap means, take a $389,900 Schertz purchase with the 2.15% first-use funding fee financed, the VA's current rate for a first-time buyer putting less than 5% down, which brings the loan to about $398,283. Principal and interest run about $2,717 a month at 7.25% and about $2,853 at 7.75%, a difference of roughly $136 a month, or about $1,600 a year, before taxes and insurance. Over a full 30-year term, that gap adds up to more than $49,000. These numbers are illustrations, and your actual loan amount, rate, and payment will depend on your lender, your funding fee status, and the market when you lock.
How far apart a lender prices your score depends on its rate sheet, so ask for quotes at your current score and at the score you could reach after some cleanup. Because discount points and lender fees sit alongside your other buyer closing costs in San Antonio, compare full Loan Estimates rather than rates alone.
Showing Strong Residual Income
VA underwriting puts unusual weight on residual income, the money left each month after your housing payment, other debts, and taxes, which has to be enough to cover everyday living costs. For a family of four in Texas on a loan of $80,000 or more, the VA's current guideline is $1,003 a month, a table the VA can revise, and it can be reduced by at least 5% for active-duty buyers who will keep using nearby base facilities.
Under current VA rules, the standard debt-to-income ratio is 41% or less, though many lenders set tighter limits of their own. A higher ratio can still be approved with written justification, and that extra review is not required when residual income beats the guideline by at least 20%. That is how a buyer with a middling score and healthy leftover income can look stronger on paper than one with a higher score who is stretched thin.
Documenting BAH Income
For active-duty buyers, Basic Allowance for Housing (BAH) can count as income. VA rules let lenders gross up tax-free military allowances when figuring your debt-to-income ratio, though residual income is figured on what you take home. How each lender documents and calculates that income can differ, so confirm its approach before you plan around a number.
That extra income can help offset a score near a lender's floor. VA rules call for your Leave and Earnings Statement and, in some cases, proof that you are authorized to live off base, so send your paperwork early. Document requirements can change as the VA and your lender update their policies.
Weighing a Joint Application
Adding a spouse as a co-borrower lets the lender count their income, but their credit history becomes part of the review too, so a spouse with weaker credit can affect the rate or the approval. How a co-borrower's credit is weighed varies by lender.
Sometimes leaving one spouse off the loan improves the terms, and sometimes their income is what makes the numbers work. Either way, the VA counts every household member in the residual income test, so have your lender run it both ways before you decide.
Rates, pricing, and underwriting guidelines change often and vary by lender, so treat these figures as a general guide and confirm current terms with a licensed lender.
Seller credits can soften the cost of a higher rate. At 672 Planters Pass in Schertz, a four-bedroom Kramer Farm home listed at $389,900 at the time of writing, the sellers are offering an $8,000 credit with an acceptable offer. A buyer may be able to put it toward a rate buydown or closing costs, within the VA's 4% cap on seller concessions and with lender approval. Seller credits and listing terms can change at any time, so confirm the current offer before you write yours.
Credit History Issues That Affect VA Loan Approval
A family carries moving boxes into their new home. Photo: Pexels.
A score is only a summary, and underwriters read the history behind it. Some events carry their own timelines under VA guidelines, and lenders may layer stricter rules on top. Here is how the most common ones are typically treated:
| Credit Event | Typical VA Guideline | What Helps Your File |
|---|---|---|
| Chapter 7 bankruptcy | Closer review within two years of discharge | Reestablished credit and a cause beyond your control |
| Chapter 13 bankruptcy | At least 12 months of on-time plan payments | Approval from the trustee or bankruptcy judge |
| Foreclosure | Reviewed under the same guidance as bankruptcy | A clean payment record since the event |
| Recent late payments | Credit generally rebuilt after 12 on-time months | Steady payments since the last late payment |
| Collections and judgments | Collections may stay open, judgments must be paid | Proof of payment on any judgment |
These timelines are a general guide drawn from VA underwriting rules, and individual lenders may require longer waiting periods or additional documentation.
Late Payments and Collections
Under VA rules, credit is generally considered reestablished after 12 months of on-time payments following the last negative item. Paying off an old debt right before you apply does not erase a poor payment record, though collection accounts do not always have to be paid off before approval. Court-ordered judgments are different and must be paid before a new loan is approved. Lenders may apply stricter standards than these VA rules, and the VA can revise the rules themselves.
Bankruptcies and Foreclosures
A past bankruptcy or foreclosure is not an automatic no. For a Chapter 7 discharge within the last one to two years, VA rules generally look for two things, new credit paid on time since the bankruptcy and a cause beyond your control, such as unemployment or medical bills insurance did not cover. A discharge within the past 12 months is usually too recent.
A foreclosure on a prior VA loan can also reduce your available entitlement until the government's loss is repaid, under the VA's current entitlement rules. Many lenders add overlays in this area, so a bankruptcy attorney and your lender can explain how your own case affects timing.
Thin Files and Missing Scores
Younger service members often face the opposite problem, too little credit history rather than a damaged one. VA rules say a recently discharged veteran's lack of credit history generally will not count against them, and the same goes for buyers who simply prefer to pay cash. Lenders handle thin files differently, and some may ask for proof of on-time rent or utility payments.
VantageScore also says its 4.0 model can score people without recent credit activity and can factor in rent payments. That only helps if your lender uses that model, so ask on the first call rather than after an application stalls.
Strengthening Your Credit Score Before a VA Home Purchase
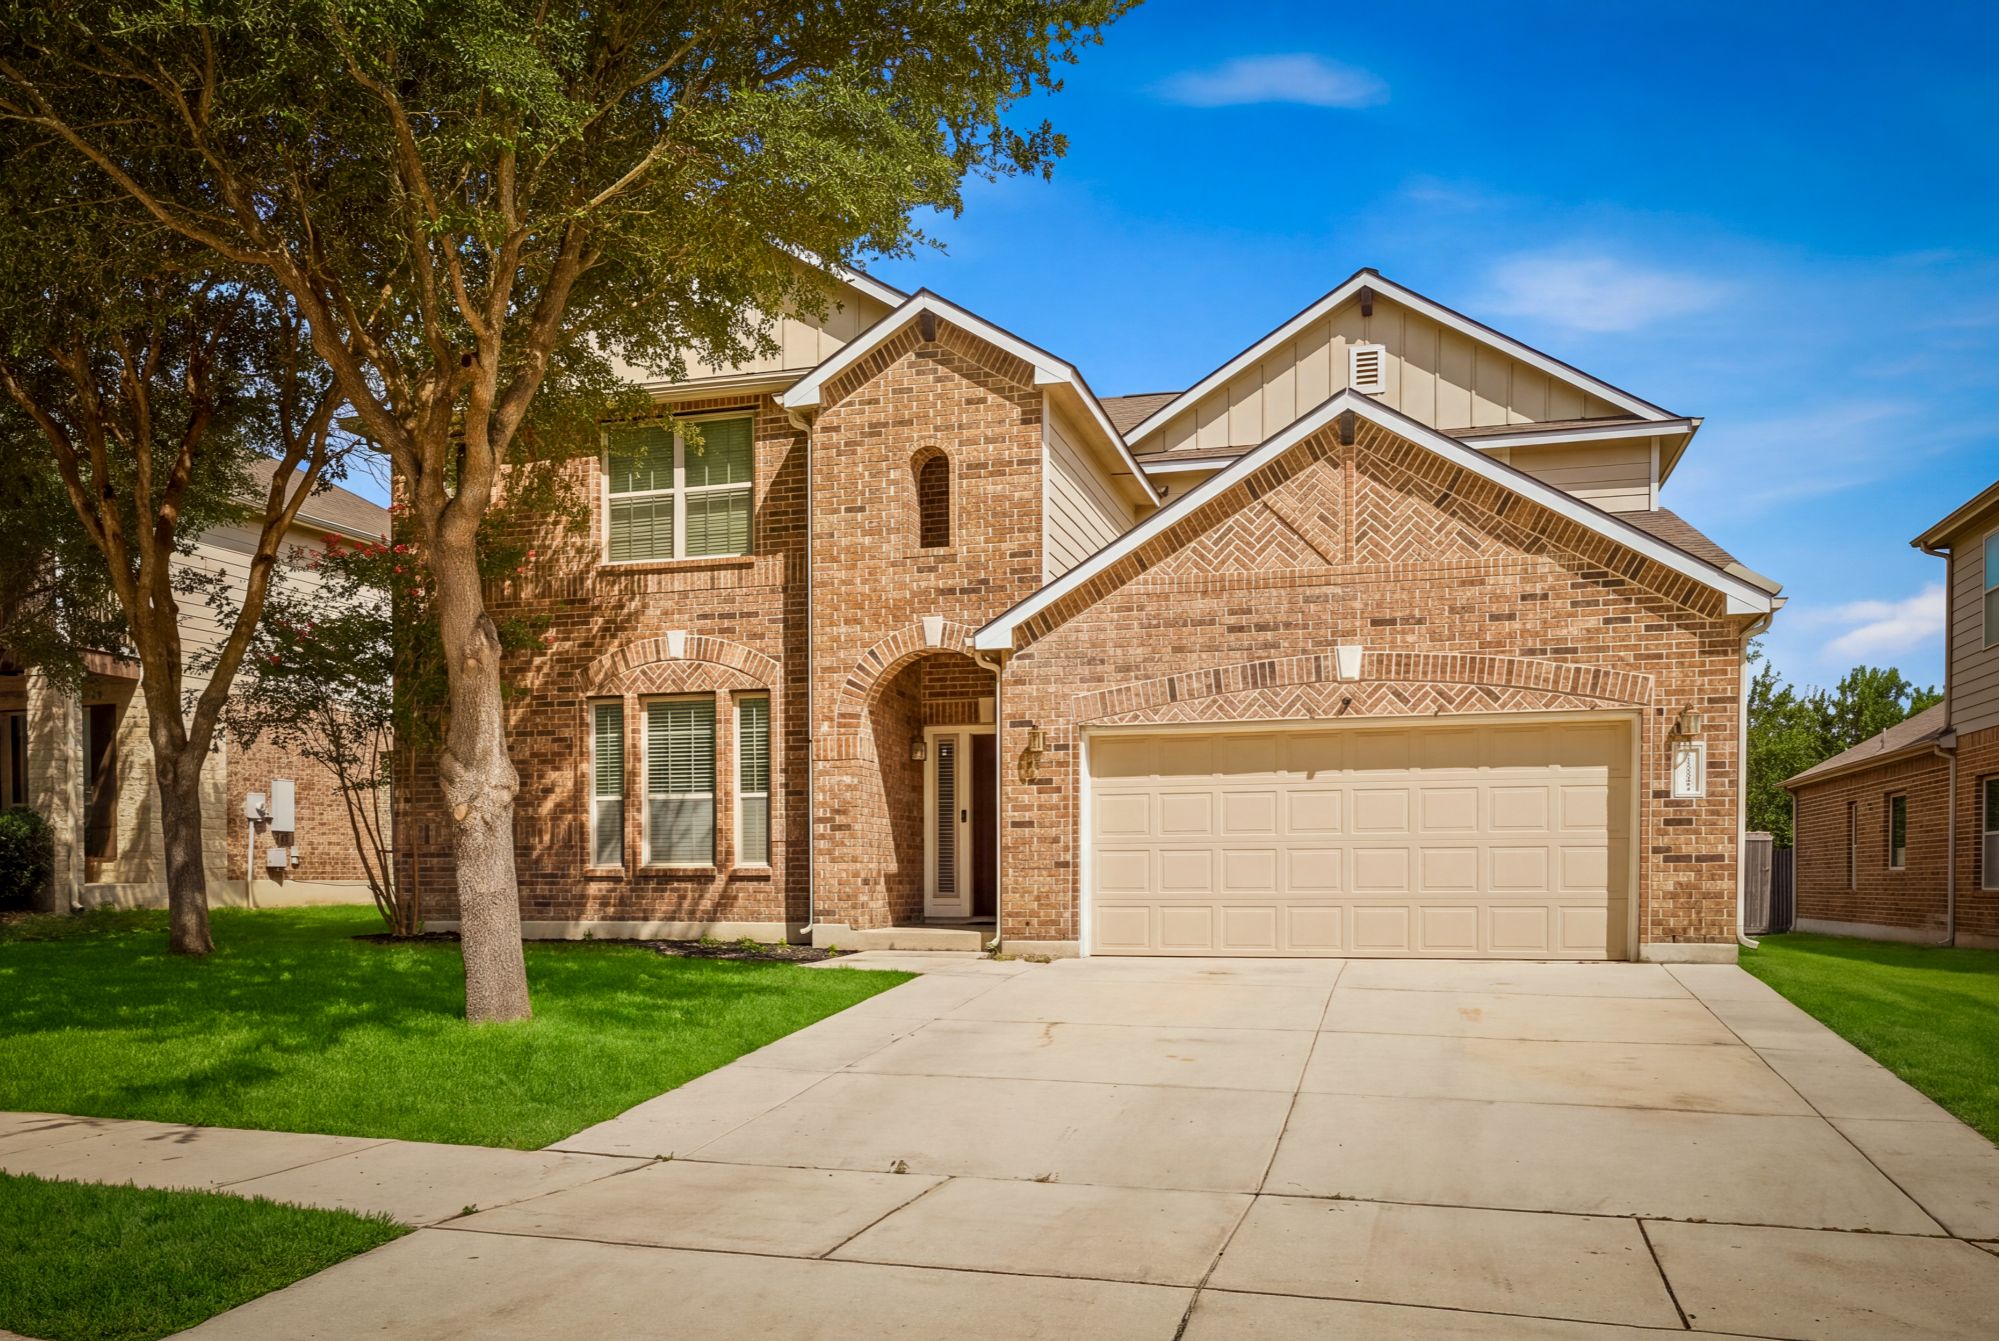
3113 Cameron Riv, Schertz, TX. Photo: Sharp Realty Group.
Small, well-timed moves can lift or protect a score in weeks rather than months. These are the steps I walk buyers through when their orders leave some runway:
Pulling All Three Reports
Start a few months before you plan to shop so any dispute has time to run its course. Free reports from all three bureaus are available through AnnualCreditReport.com, and active-duty service members and National Guard members can sign up for free electronic credit monitoring from Equifax, Experian, and TransUnion. Each bureau sets its own enrollment steps, and the free offerings can change over time.
Look for accounts you do not recognize, wrong balances, and late payments that never happened, and leave time to fix them before a lender pulls your file.
Paying Down Card Balances
The Consumer Financial Protection Bureau (CFPB) points to two habits for building and keeping a good score, paying every bill on time and keeping card balances low compared with your credit limits. Paying down cards that sit close to their limits is a practical place to start, and the lower balances count once your card issuers report them. How much your score moves depends on the scoring model and the rest of your credit history.
Correcting Report Errors
Dispute inaccurate items directly with the credit reporting company, and keep copies of what you send. The company generally must investigate within 30 days, or up to 45 days in some cases, and then has five business days to send you the results. These timelines come from current federal rules, which regulators may update.
When the company that supplied the wrong information corrects it, that company has to send the fix to every bureau it reported to. Once a correction posts, ask your lender how soon your file can be updated before you lock a rate, since that timing depends on each lender's process.
Timing Lender Comparisons
Because overlays differ, it makes sense to compare more than one lender when your score sits near a cutoff. The CFPB also notes that scoring models generally treat mortgage inquiries within a 14- to 45-day window as a single inquiry, with the exact window depending on the scoring model, so keep your rate shopping tight. Running that comparison before you request mortgage pre-approval in San Antonio means the letter you hand a seller reflects your strongest file.
Using Military Credit Protections
Under the Servicemembers Civil Relief Act, you can ask lenders to cap interest at 6% on eligible loans you took out before entering active duty, and the interest above 6% is forgiven while you serve. That may lower payments and free up room in your ratios. You can also place an active-duty alert on your credit reports before you deploy. Eligibility and request steps depend on federal law and each creditor's process, both of which can change, so your installation's financial readiness office or a legal assistance attorney can explain how these protections apply to your accounts.
Pausing New Credit Applications
Under current VA rules, credit reports can be no more than 120 days old when you sign at closing, and lenders have to explain any new information that turns up on an updated report. The CFPB suggests avoiding new credit applications right before and during the mortgage process, so steer clear of these common missteps until you close.
- Opening a new credit card, even for a store discount at checkout.
- Financing furniture, appliances, or a vehicle before you have the keys.
- Closing old credit cards, which can raise the share of your limits you are using.
- Co-signing a loan for a family member or friend.
- Missing a payment during the move instead of setting up autopay before pickup day.
- Moving large sums between accounts without a paper trail your lender can follow.
These timeframes are a general guide, and how quickly any change shows up depends on when your creditors report and on your lender's process.
A cleaner score can widen which homes fit your payment, which matters when your family needs more room. When you tour 3113 Cameron Riv in Schertz, you will find five bedrooms and three full baths across 3,526 square feet in Fairway Ridge, with a brand-new heating and air conditioning system and two bedrooms on the main level. It was listed at $429,900 at the time of writing, is zoned to the Comal Independent School District, and, like Planters Pass, accepts VA financing. Price, availability, and listing details can change, so confirm them before you schedule a showing.
Buying Near JBSA With Confidence in Your Credit
That 14-point gap from the first lender call should look different now. It reflects one company's policy, not the VA's, and it sits inside a bigger picture that includes your residual income, payment history, BAH, and the steps you can still take before an offer. A score near a lender's floor is a reason to plan, compare, and sometimes take a few weeks to fix an error, not a reason to set aside a benefit you earned in uniform.
With your reports reviewed, your balances in check, and a lender who reads the whole file, you can tour homes near Randolph, in Schertz, or around Cibolo knowing where your financing stands. Because a PCS puts your timeline, offer, and loan on the same clock, choosing a military relocation specialist who has used the VA benefit firsthand can keep all three moving together.
Ready to Map Out Your VA Credit Plan?
I am Anthony Sharp with Sharp Realty Group, a U.S. Air Force veteran who helps military families and civilian buyers put their VA benefit to work across San Antonio, Schertz, Cibolo, and the JBSA corridor. Whether your score is ready today or needs a few months of work, I can connect you with a lender who knows VA files and build a home search around a payment that fits.
Call or text: 210-997-0763
Schedule a time: book a consultation
Email: anthony@sharprealtygrouptx.com
Office: 213 Terramar, Cibolo, TX 78108
Frequently Asked Questions (FAQs)
What is the minimum credit score for a VA loan in 2026?
The VA does not set one. Each lender chooses its own floor, and many look for at least 620, while some will work with scores in the 500s. Lender floors can change at any time, so confirm the current requirement before you apply.
A denial from one lender does not rule out a VA loan, so it can pay to compare lenders whose overlays fit your score.
Can I get a VA loan with a 580 credit score in San Antonio?
It may be possible with a lender whose overlay allows it, though expect a closer look at your recent payment history and possibly a higher rate.
Compensating factors such as high residual income, long-term employment, and minimal consumer debt can help balance out the score, and a licensed lender can tell you whether your full file supports an approval.
Does my credit score affect my VA loan interest rate?
Yes. Your lender sets your rate and points, and your credit score is one of the factors it weighs. On a $389,900 Schertz purchase, the gap between 7.25% and 7.75% works out to roughly $136 a month in principal and interest. Actual pricing depends on each lender's rate sheet and the market, but even a modest score improvement can matter over the life of the loan.
How long after bankruptcy can I get a VA loan?
For a Chapter 7 discharge within the last two years, VA rules generally look for reestablished credit and a cause beyond your control, and a discharge within the past 12 months is usually too recent. A Chapter 13 plan may allow a purchase after 12 months of on-time payments with approval from the trustee or bankruptcy judge.
Lenders can set longer waiting periods, so confirm the timeline with your lender and a bankruptcy attorney.
Does BAH count as income for a VA loan?
Generally, yes. VA rules let lenders gross up tax-free military allowances for the debt-to-income ratio, while residual income uses your actual take-home pay. Have a recent Leave and Earnings Statement ready, along with any off-base housing authorization your lender requests. Documentation rules can vary by lender and may change with VA guidance.
How fast can I raise my credit score before a PCS?
Lower card balances count once your card issuers report them, and a dispute generally takes 30 to 45 days to investigate, though reporting schedules vary by creditor and timelines may shift.
Starting a few months before you shop leaves room for both, which helps keep a PCS schedule intact.
* * *
Disclaimer: This article is general information only and does not consider your individual financial, tax, or legal circumstances. Credit score requirements, lender overlays, mortgage rates, VA guidelines, and listing details change and are provided as a general guide, not a guarantee. Nothing here guarantees financing, approval, appreciation, or resale value. Before making a decision, speak with a qualified professional such as a REALTOR®, a licensed lender, or an attorney about your specific situation.
Categories
- All Blogs (267)
- BAH (3)
- For Home Buyers (186)
- For Home Sellers (89)
- For Investors (41)
- For Military Service Members (179)
- For Renters (9)
- JBSA (6)
- Local Events (12)
- Local Real Estate News (39)
- Market Updates (41)
- Military Relocation (40)
- Neighborhood Tours (57)
- PCS Move (106)
- Property Tours (5)
- VA Loans (13)
Recent Posts