Homeowners Insurance in Cibolo & Schertz: 2026 Buyer Guide
Start shopping homeowners insurance for a Cibolo or Schertz home during your option period, not during closing week. Roof age, the wind and hail deductible, and the home's claim history drive most quotes, and your lender needs the policy bound before final loan approval. Flood coverage is a separate policy, so check the flood zone before you commit.
Key Takeaways
- Get insurance quotes during the option period so a surprise premium or a declined roof shows up while you can still renegotiate or walk away.
- Your lender needs the policy bound and the declarations page in hand before final approval, so coverage is a closing task, not a move-in task.
- Roof age, the percentage wind and hail deductible, and past claims on the home move quotes more than almost anything else.
- A standard homeowners policy does not cover flood, so check the flood zone early and decide on a separate flood policy before closing.
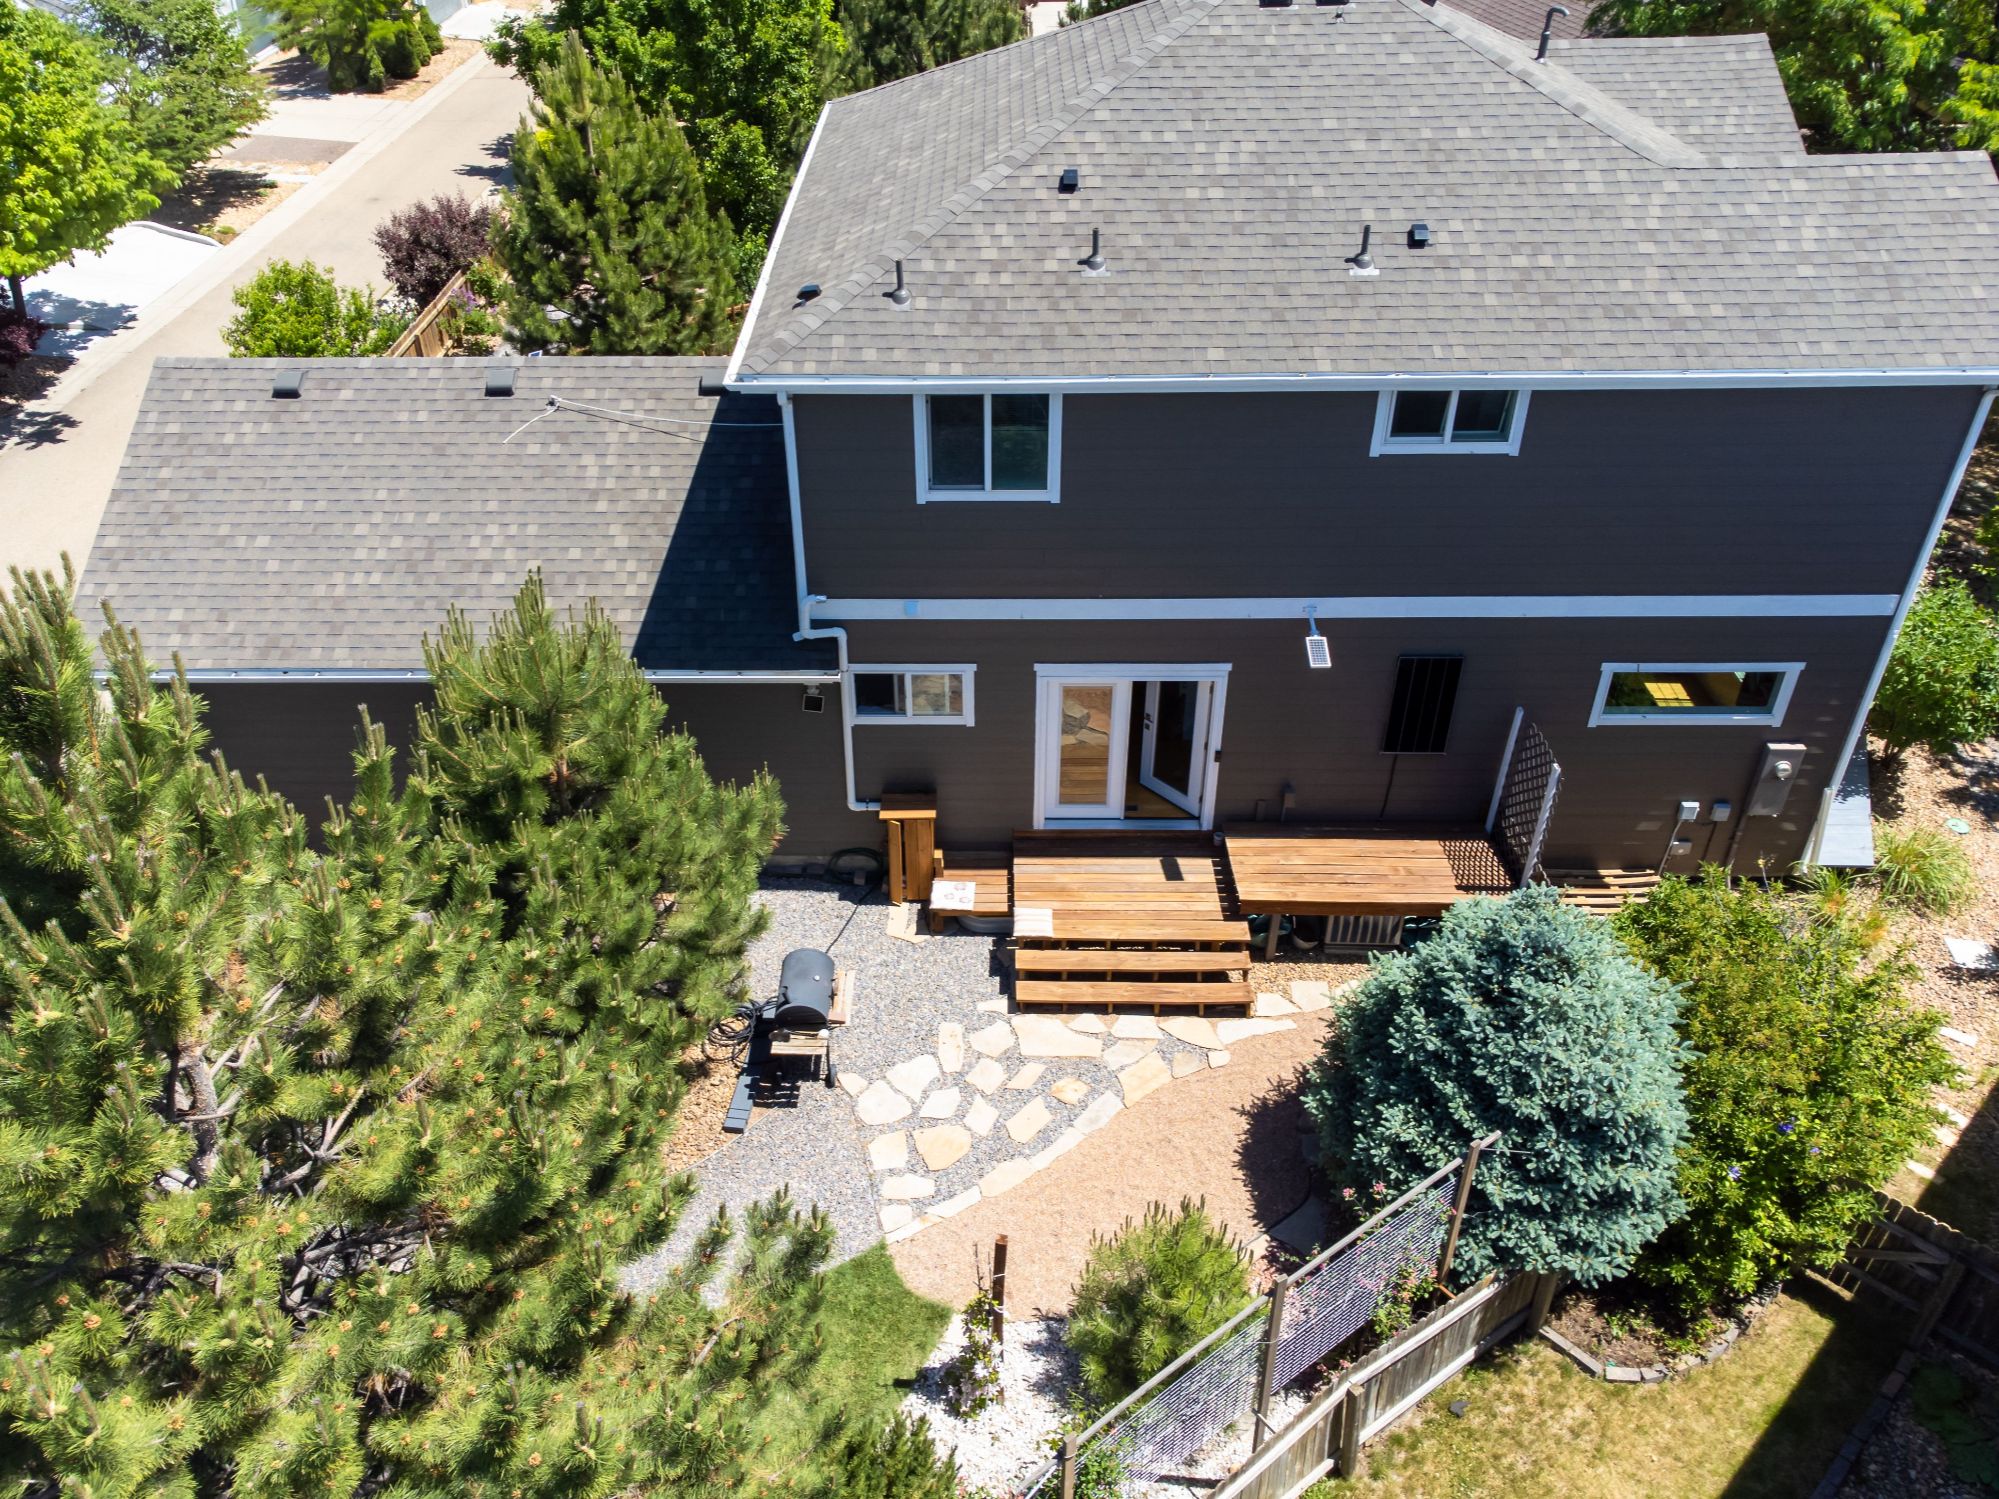
The roof on this house will shape your insurance quote as much as the price will. Photo: Pexels.
Your offer on a home in Cibolo just got accepted, the inspection is booked, and your lender sends a short email asking for your homeowners insurance declarations page. Many buyers have not even requested a quote yet. A week later, they learn the roof is too old for the first company they called.
I am Anthony Sharp, a 9-year enlisted U.S. Air Force NCO and REALTOR® with Sharp Realty Group, and I live in Cibolo. I have helped more than 100 military families buy and sell around Joint Base San Antonio (JBSA), and my VA closings typically land in 25 to 35 days. Insurance is one of the quiet steps inside that window, and my VA loan closing timeline shows exactly where it fits.
This guide covers when to shop, what drives your quote in Cibolo and Schertz, how the wind and hail deductible works, and where flood coverage comes in. The goal is simple. Your policy should be ready before your lender asks for it, and the number should not surprise you.
Why Homeowners Insurance Matters When Buying in Cibolo or Schertz
Insurance is easy to treat as paperwork, but it affects your loan approval, your monthly payment, and how much cash you could owe after a storm. Here is how it fits into the purchase:
What Your Lender Requires Before Closing
Every mortgage lender I work with requires homeowners insurance on the home before the loan can fund, and VA loans are no exception. The lender usually wants the declarations page, the policy number, the effective date, and the lender's name listed correctly as the mortgagee. Missing or wrong details on that page are a small but common reason a file sits waiting for final approval.
In most purchases, the first year's premium is paid at or before closing, and the lender sets up an escrow account to collect future premiums with your monthly payment. That means the premium you choose now becomes part of the payment you live with every month.
What a Texas Homeowners Policy Covers
A homeowners policy generally covers the structure, your belongings, extra living costs while the home is being repaired after a covered loss, and personal liability. In Texas, insurers can use their own policy forms, so two quotes with the same price can cover very different things. Water damage, foundation damage, and roof coverage are the areas where I see policies differ most.
Homeowners insurance is also different from title insurance. Title insurance protects your ownership rights from past problems, and my guide to title insurance in Texas covers how that policy works. Homeowners insurance protects the house and what is in it going forward.
What Texas Insurance Costs Right Now
The Texas Department of Insurance (TDI) lists the statewide average homeowners premium at $3,506 a year for 2025, a preliminary figure in its market overview (TDI, June 2026). TDI also reported that wind and hail have made up an average of 62% of homeowners losses in Texas since 2019 (TDI, June 2026).
A statewide average is only a starting point. Your actual premium depends on the home, the roof, the coverage you pick, your deductible, and the company. The only number that matters for your budget is the quote on the specific house you are buying.
When to Shop for Homeowners Insurance During Your Purchase
Comparing quotes early gives you time to ask questions before closing week. Photo: Pexels.
Timing is where most insurance problems start, and it is also the easiest part to fix. Here is when each step should happen:
Starting Quotes During the Option Period
The option period is the window in your contract when you can inspect the home and back out for any reason. I tell my buyers to request insurance quotes in the first few days of it, right after the contract is signed. If a company declines the roof or the premium comes back much higher than you planned, you still have time to negotiate a roof repair or credit, or to walk away.
Send your insurance agent the property address, the year built, the square footage, and anything you know about the roof. Once you have the inspection report, share the roof section with them too. Better information up front means fewer surprises when the company does its own review.
Binding the Policy Before Final Approval
Binding means the insurance company has agreed to cover the home starting on a specific date, usually your closing date. Pick your policy once the inspection and any repair negotiations are settled, then have your agent send the declarations page straight to your lender and title company.
Ask your agent to confirm the effective date matches the closing date in your contract. When closing moves, update the policy the same day so your coverage and your loan line up.
Shopping From Your Current Duty Station
You do not need to be in Texas to insure a Texas home. Quotes, applications, and policy documents are usually handled by phone and email. If you are relocating on permanent change of station (PCS) orders, make sure the company you call can write policies in Texas, since not every company or agent that covers your current home is licensed here.
Ask about any inspection the company may schedule after closing. Some insurers send someone to photograph the exterior and roof in the first weeks of the policy, and knowing that ahead of time avoids confusion while you are still in transit.
What Drives Homeowners Insurance Quotes in Cibolo and Schertz
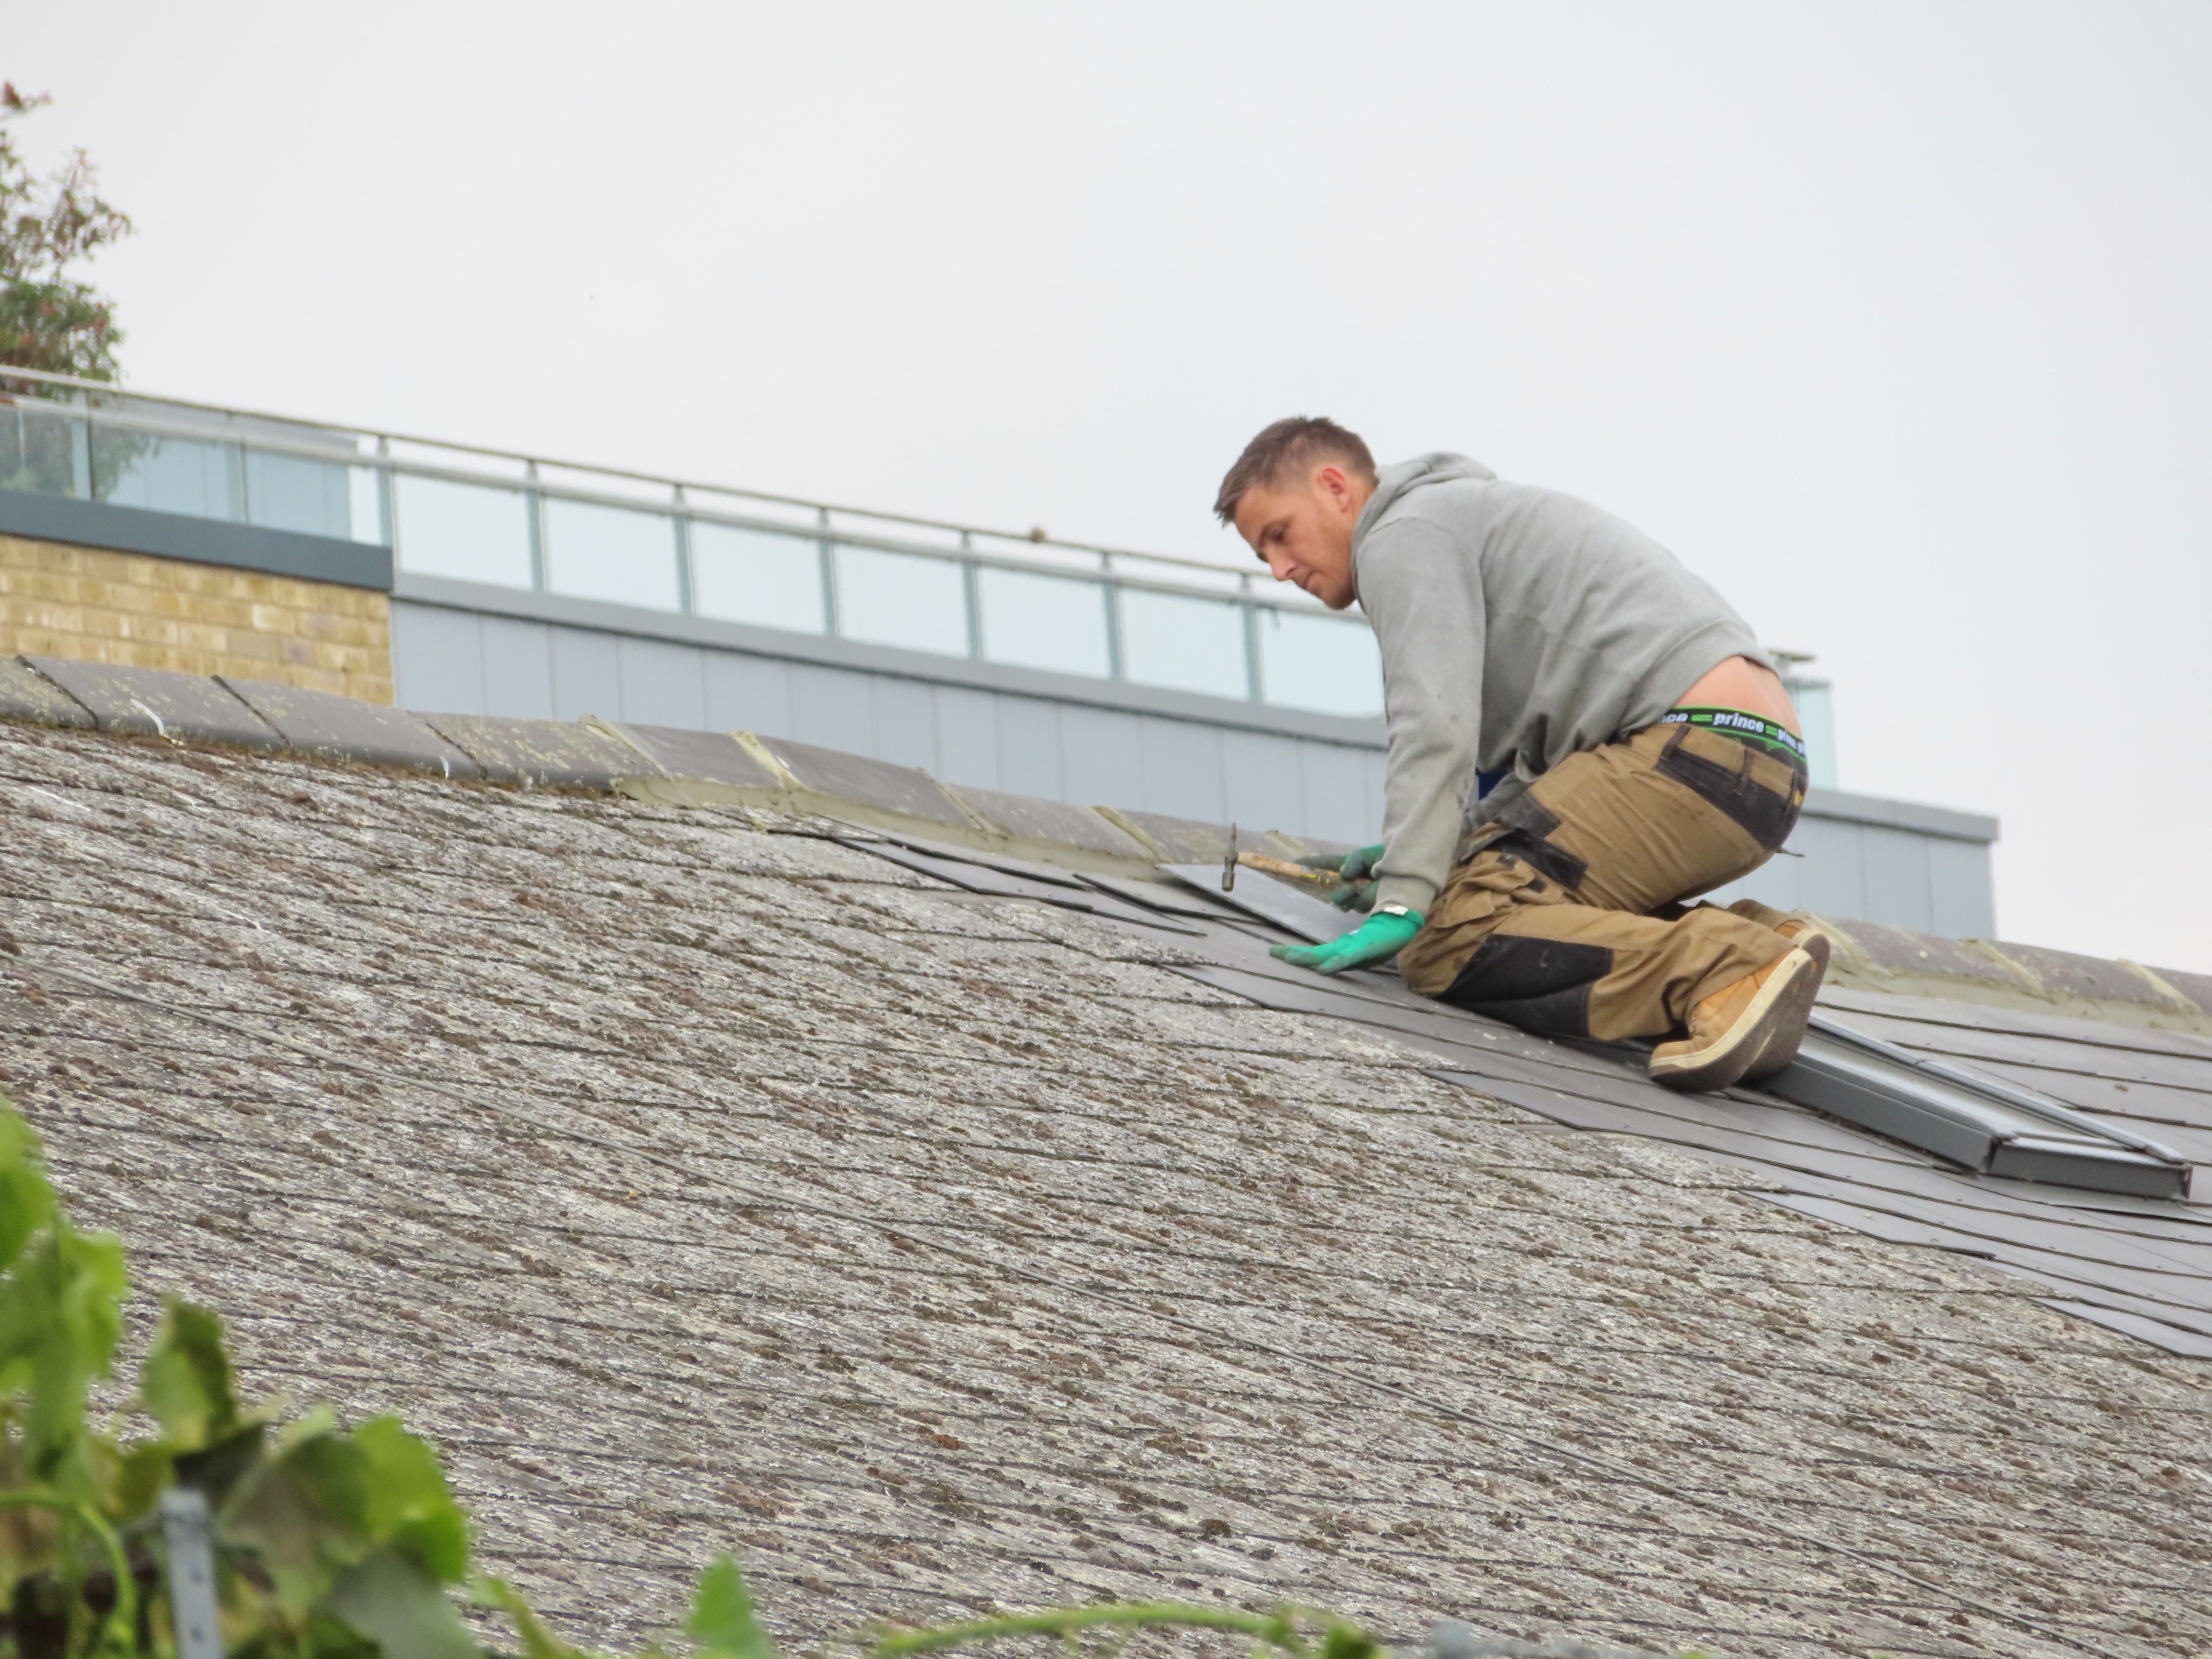
Roof age and condition come up in almost every insurance conversation. Photo: Pexels.
Two homes on the same street can get very different quotes. These are the factors that usually make the difference:
Roof Age and Material
The roof is the first thing most insurers ask about. An older roof can mean a higher premium, a narrower list of companies willing to write the policy, or roof coverage that pays actual cash value instead of replacement cost. Actual cash value subtracts depreciation, so an older roof damaged by hail may pay out far less than the cost of a new one.
Ask the listing agent early for the roof's age and any replacement paperwork. Some roofing materials are rated for impact resistance, and certain insurers may offer a discount for them. Ask each company whether that applies before you assume it does.
Wind and Hail Deductibles
Many Texas policies carry two deductibles. One applies to most claims, like fire or theft, and is a set dollar amount. A separate deductible applies to wind and hail damage and is often a percentage of the home's insured value, not a percentage of the claim.
Here is an example of how that works. On a home insured for $350,000 with a 2% wind and hail deductible, you would pay the first $7,000 of a hail claim yourself. A quote with a lower premium and a higher percentage deductible may cost you more after a single storm, so compare both numbers together.
This example is for illustration only. Deductible options vary by company and policy.
Past Claims on the Property
Insurers can look at the claim history tied to a property, not just to you. A home with a recent water or roof claim may get a higher quote or more questions. Ask the listing agent whether the sellers have filed insurance claims and whether the work was completed, and keep any repair invoices the sellers share.
Replacement Cost and Coverage Limits
Your dwelling coverage should reflect what it would cost to rebuild the home, which is not the same as the purchase price or the appraised value. The land does not need to be rebuilt, but labor and materials do. Ask how the company estimated rebuilding cost, and whether the policy includes extra coverage for rising construction costs or required code upgrades.
Higher limits raise the premium, and the percentage wind and hail deductible rises with them. That is one more reason to look at the full declarations page instead of the premium alone.
Flood Insurance Questions for Cibolo and Schertz Buyers
A standard homeowners policy does not cover flood damage, even in Texas. Flood is its own decision, and it is worth making before you close:
Checking the Flood Zone Before You Offer
The Federal Emergency Management Agency (FEMA) maps flood zones across the country, and your lender will order a flood determination on the property during the loan process. You do not have to wait for it. Ask your agent to help you check the address against FEMA's maps when you are touring, especially for homes near creeks or drainage areas.
Lot slope and drainage matter too, and my backyard and lot checklist covers what to look for while you walk the property.
Meeting Lender Flood Requirements
When a home sits in a high-risk flood zone, federal rules require flood insurance on a federally backed mortgage, including a VA loan. Under the National Flood Insurance Program (NFIP), a new policy usually has a 30-day waiting period, but FEMA waives it when the policy is bought in connection with a loan closing (FEMA). Your insurance agent and lender will coordinate the effective date, so loop them in as soon as the flood determination comes back.
Weighing Flood Coverage Outside a Mapped Zone
A home outside a high-risk zone does not need flood insurance for the loan, but heavy Texas rain does not always follow the map. Ask for a flood quote anyway. Policies for lower-risk zones often cost less, and having the number lets you decide based on facts instead of guesses. You can learn more about how flood coverage works at FEMA's FloodSmart site.
How to Compare Homeowners Insurance Quotes in Cibolo and Schertz
A fair comparison means lining up the same coverage across every quote. Before you choose, check these points:
- Use the same dwelling coverage amount on every quote so the premiums are comparable.
- Convert each wind and hail deductible into dollars and put it next to the premium.
- Confirm whether the roof is covered at replacement cost or actual cash value.
- Ask how each policy handles water damage and foundation damage, since these vary by company.
- Check whether the company is licensed in Texas and how claims are reported.
- Get a separate flood quote, even if the home is outside a high-risk zone.
- Ask what discounts apply, such as bundling, impact-rated roofing, or monitored alarms.
Treat this list as a general guide. A licensed insurance agent can explain how each policy applies to the specific home you are buying.
Closing on Your Cibolo or Schertz Home With Coverage in Place
Insurance stops being a last-minute scramble once you treat it as part of the option period. You get quotes while you can still negotiate, you see the real cost of the roof and the deductible, and your lender gets the declarations page before anyone has to ask twice.
That leaves closing week for what it should be about, signing, getting the keys, and planning the move in. The policy is already in place on day one.
Frequently Asked Questions (FAQs)
When should I get homeowners insurance when buying a house in Texas?
Request quotes in the first few days of your option period, then bind the policy once the inspection and repairs are settled. Your lender needs the declarations page before final approval, so waiting until closing week can delay your loan.
Does a VA loan require homeowners insurance?
Yes. VA lenders require homeowners insurance on the home before the loan can close, and flood insurance is also required when the home is in a high-risk flood zone. Your lender will tell you the exact coverage and paperwork they need.
Does homeowners insurance cover flooding in Cibolo or Schertz?
No. A standard homeowners policy does not cover flood damage. Flood coverage is a separate policy through the NFIP or a private insurer, and it is worth getting a quote even when the home is outside a high-risk zone.
How does a wind and hail deductible work in Texas?
Many Texas policies use a percentage of the home's insured value as the wind and hail deductible. On a home insured for $350,000, a 2% deductible means you pay the first $7,000 of a covered wind or hail claim. Always convert the percentage to dollars before you compare quotes.
Can an older roof affect my homeowners insurance?
Yes. An older roof can raise your premium, limit which companies will cover the home, or mean the roof is covered at actual cash value instead of replacement cost. That is why Sharp Realty Group asks about roof age early, so buyers can get quotes during the option period while there is still room to negotiate.
Can I buy homeowners insurance before I arrive at JBSA?
Yes. Quotes and policies are usually handled by phone and email, so you can insure the home from your current duty station. Just confirm the company is licensed to write policies in Texas.
Plan Your Cibolo or Schertz Purchase With Insurance in Mind
Tell me your report date and the homes you are considering, and I will help you map out when to get insurance quotes, inspections, and every other step so your closing stays on schedule.
Sharp Realty Group, 213 Terramar, Cibolo, TX 78108
* * *
Disclaimer: This article is general information only and does not consider your individual financial, insurance, or legal circumstances. Insurance coverage, pricing, deductibles, and lender requirements vary by company, property, and transaction, and the figures here are a general guide, not a quote or a guarantee. Nothing here guarantees financing, approval, coverage, appreciation, or resale value. Before making a decision, speak with a licensed insurance agent, a licensed lender, or a REALTOR® about your specific situation.
Categories
- All Blogs (305)
- BAH (4)
- Buying Process (1)
- Cibolo (2)
- For Home Buyers (209)
- For Home Sellers (96)
- For Investors (45)
- For Military Service Members (201)
- For Renters (10)
- Home Inspections (1)
- JBSA (9)
- Local Events (12)
- Local Real Estate News (41)
- Market Updates (44)
- Military Relocation (46)
- Neighborhood Tours (58)
- PCS Move (119)
- Property Tours (7)
- Schertz (2)
- VA Loans (21)
Recent Posts