BAH Rate Protection in San Antonio: 2026 JBSA Buyer Guide
Key Takeaways
- Under current DoD rules, BAH rate protection keeps your allowance at the higher of the new January 1 rate or your December 31 amount, so a published cut does not shrink BAH you already receive.
- A PCS, a reduction in pay grade, or a change in dependency status resets you to the current published table.
- Every JBSA installation shares one housing area, so buying in Schertz, Cibolo, or Converse does not change your allowance.
- Budget the mortgage from the published rate for your grade, and confirm how your lender treats BAH before you write an offer.
Downtown San Antonio at sunset. Photo: Pexels.
You have orders to Joint Base San Antonio (JBSA), a home search ahead of you, and one question holding you back from signing. What happens to the mortgage payment if your Basic Allowance for Housing (BAH) drops after closing? San Antonio's 2026 rates already came in below 2025, and the 2027 table is expected in December, so it is a fair thing to ask.
BAH rate protection answers most of that question. I am Anthony Sharp, a U.S. Air Force veteran and REALTOR® with Sharp Realty Group in Cibolo, and the JBSA corridor is the market I work every week. Before you plug your pay grade into the JBSA BAH calculator and set a price range, it helps to know what rate protection covers and where it stops.
The rule protects the allowance you already draw, not the rate a newly arriving service member starts on, and one change in your orders or family status can end it. Once you know those limits, you can choose a payment that holds up for the whole tour.
How BAH Rate Protection and JBSA Rates Work
Rate protection sits on top of how BAH itself is set, so it helps to see both pieces before you sign a 30-year note. The Department of Defense (DoD) sets the rates and the protection rule, and the Defense Travel Management Office (DTMO) publishes them each year:
The Higher-of-Two-Rates Rule
Under current DoD policy, each January 1, the new rate published for your grade and duty station is weighed against what you were paid on December 31, and you receive the higher of the two. A rate increase reaches your paycheck, and a rate cut does not.
That protection holds as long as nothing about your eligibility changes, meaning no permanent change of station (PCS), no reduction in pay grade, and no change in dependency status, though DoD can revise these rules. It also explains why two neighbors in Universal City with the same rank and family size can show different BAH amounts on their Leave and Earnings Statement (LES), depending on when each one reported to JBSA.
The Promotion Exception
A promotion moves you to the current published rate for your new grade, which is usually a raise. In the uncommon case where that rate is lower than what you were already drawing, as can happen in a year like 2026 when San Antonio's table moved down, DoD guidance lets you keep the higher amount, though your finance office makes the final call on your entitlement.
The Single JBSA Housing Area
Randolph Air Force Base (AFB), Fort Sam Houston, Lackland AFB, and Camp Bullis share one San Antonio military housing area, so under today's boundaries, which DoD sets and can redraw, your rate is the same no matter which gate is on your orders. BAH also follows your duty station, not your home address.
That means a family buying in Schertz, Cibolo, Converse, or on the far west side of San Antonio draws the same allowance at the same grade. Where you buy comes down to commute, schools, property taxes, and the home itself.
The Rental-Based Formula
According to DoD's 2026 rate release, BAH is built from local median rents plus utilities such as electricity, heat, and water and sewer. Mortgage payments never enter the math, and DoD is clear that the allowance is not meant to cover every housing expense.
The 2026 JBSA BAH rates run from about $1,359 a month for an E-1 without dependents to about $2,475 for an O-6 with dependents, and an E-5 with dependents receives about $1,869. Many of those San Antonio rates came in below 2025 levels, even though BAH rose an average of 4.2% nationwide.
These figures and rules reflect DoD guidance as published for 2026 and can change with each annual release, so confirm your exact rate and status with your finance office.
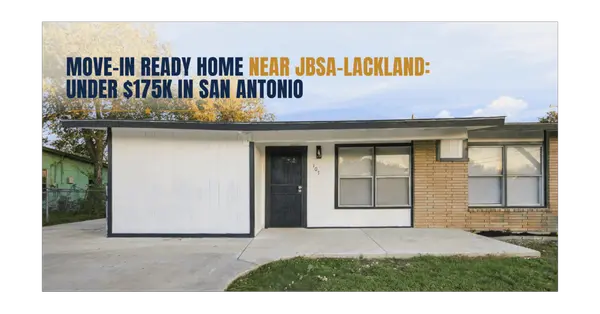
For buyers working with a tighter budget, 103 Chadwick Dr near Lackland is a three-bedroom, single-story Valley Hi home on a corner lot in San Antonio, listed at $172,000 at the time of writing.
What Ends BAH Rate Protection for JBSA Families

Move-in day, with boxes still to unpack. Photo: Pexels.
Protection carries over from one year to the next until your status changes. When one of these events ends it, you move to the published table for your new situation, and as the rules stand today, that new amount is protected from then on:
Receiving PCS Orders
A PCS is the most common way protection ends. Your protected JBSA amount stays behind, and at the next duty station you start on that area's current rate, which your gaining finance office can confirm. The same rule works in reverse for families arriving here, who start on the 2026 San Antonio table rather than any higher 2025 rate.
Dropping a Pay Grade
A demotion moves your allowance to the rate for the lower grade. It is uncommon, but it is one of the few events that can lower BAH while you stay in the same house.
Changing Dependency Status
Marriage, divorce, or a change in custody can move you between the with-dependents and without-dependents rates. BAH only looks at whether you have dependents, not how many.
At JBSA in 2026, the gap between those two rates is about $369 a month at several enlisted grades, including E-1 and E-5, though that difference may shift when new rates are published. That is enough to shift a mortgage budget in either direction, so run the payment at both rates when a change is on the horizon.
Leaving Active Duty
Separation and retirement are not among the three events that end protection, because BAH stops altogether when active service ends. For a homeowner, that matters more than any rate cut.
A buyer within a year or two of separating should plan the mortgage around post-service income, such as a civilian salary, retirement pay, or disability compensation, and ask a lender how each source is counted, since lenders weigh post-service income differently.
Eligibility rules differ for dual-military couples, Reserve and Guard members on active duty, and service members with custody arrangements, so your finance office is the right place to confirm your specific status.
For families on fresh orders who need space for guests or a home office, 3113 Cameron Riv in Schertz is a five-bedroom Fairway Ridge home with two bedrooms on the main level, roughly 10 minutes from Randolph and listed at $429,900 at the time of writing.
Buying a Home Near JBSA With BAH Rate Protection in Mind
A for-sale sign out front. Photo: Pexels.
Knowing how protection works is half the job. The other half is building a mortgage plan that does not lean on it too hard, since a loan runs on a longer clock than any assignment:
Budgeting From the Published Rate
When you are already rate protected, it is tempting to size the payment to that higher figure. I usually suggest budgeting from the current published rate for your grade instead, because a status change would drop you to that number, and the difference becomes a cushion for the rest of the tour.
From there, some buyers pick a home a notch below their allowance and keep the difference, while others stretch for a newer build with lower early maintenance. Which path fits depends on what BAH in Schertz and Cibolo covers at your grade.
Qualifying With Your Lender
Lenders verify military income, BAH included, from your LES. For loans backed by the U.S. Department of Veterans Affairs (VA), the VA's lender handbook calls for the LES and has lenders look closely at anyone within 12 months of leaving active duty, so the service time left after closing matters. VA can update these guidelines, and lenders may add requirements of their own.
Conventional lenders follow their own guidelines, and how a rate-protected amount is treated can vary by lender and loan program. Ask your loan officer early which BAH figure they will use and what documents they need, especially when your end-of-service date or next set of orders falls inside the first year of the loan.
Checking Your LES Before Underwriting
Before a lender pulls your file, put the BAH line on your most recent LES next to the published 2026 rate for your grade. A higher LES figure usually means you are rate protected, and pointing that out to your loan officer early keeps the two numbers from causing confusion in underwriting. When the difference is hard to explain using the rules in the DTMO BAH guidance, your finance office is the official source for answers.
Leaving Room for Taxes and Insurance
Because BAH is built from rents, it leaves out Texas property taxes, homeowners insurance, and homeowners association (HOA) dues, which can add several hundred dollars to a monthly payment in the corridor. For illustration, the most recent tax record on one of my current listings, a 2013 home in Schertz, shows about $6,093 a year, or roughly $508 a month before insurance. Tax bills change each year with appraisals and local rates, so the current figure may differ. I protest my own appraisals most years, so I always check the tax line before I look at the floor plan.
Mortgage rates add pressure too. The Freddie Mac 30-year fixed average climbed to 7.40% as of October 8, 2026, up from 7.28% a week earlier, and because that survey tracks conventional loans, VA loan quotes can differ. Rates move weekly, so get a current quote from your lender before you lock.
Planning Around the 2027 Release
The last three tables came out in mid-December, on December 15, 2023, December 13, 2024, and December 11, 2025, each for a January 1 start. The 2027 table will likely follow that pattern, and nobody outside DoD knows whether San Antonio's rates will rise or fall.
For a service member already stationed here, a cut would not touch the current allowance. For a family reporting around the turn of the year, arriving before or after January 1 could affect which table applies. Few families control their report date, but ask your finance office anyway before you lock a budget.
Lender requirements, mortgage rates, and tax figures change often, so treat these as a general guide and confirm current numbers with a licensed lender and your county appraisal district.
For buyers aiming to keep the payment below their allowance, 672 Planters Pass in Schertz is a four-bedroom Kramer Farm home with the primary suite on the main floor, listed at $375,000 at the time of writing, with an $8,000 seller credit available on an acceptable offer, terms the sellers can change. All three homes I mentioned list VA financing as an accepted option, though final approval rests with the lender.
BAH Rate Protection for JBSA Homeowners, Sellers, and Investors
Rate protection keeps shaping your finances after closing, especially once the next set of orders arrives and the house has to work without your JBSA allowance behind it:
Refinancing the Home Before a PCS
A homeowner who refinances while still stationed at JBSA will usually be qualified on the BAH shown on the current LES. When pending orders or a separation date fall within the first year of the new loan, expect more questions, and the lender may limit how much of that income it counts. Confirm the lender's approach before you pay for an appraisal.
Renting the Home After a PCS
Once you leave, the property has to stand on local rent, not your allowance. I self-manage rental homes in this corridor, and the full math includes vacancy between tenants, routine and surprise repairs, a property manager if you will be far away, and a Texas property tax bill every year.
Military rental demand tends to cycle with PCS season, which can help a JBSA-area rental, but run the numbers before you count on rent covering the mortgage, and talk with a tax professional before you rely on any particular return.
Selling the Home Before a PCS
The San Antonio Board of REALTORS® (SABOR) reported a median sale price of a little over $299,000 for August 2026, with the average home spending about 82 days on the market, longer than a year earlier. These numbers shift month to month, and your neighborhood may run differently. Listing two to three months before a report date can leave room to negotiate rather than react.
Anyone planning to buy again at the next station with a VA loan should ask a lender how the sale affects restoring their entitlement, so the benefit is ready for the next house, keeping in mind that VA sets the restoration rules.
Market figures, rental conditions, and loan rules shift month to month, so use these as a general guide and confirm details with your lender, a tax professional, and your agent.
Buying Near JBSA With a BAH Plan That Holds Up
So what happens to the mortgage if BAH drops? For a service member who stays put with the same grade and family status, a lower published rate does not reduce the allowance already being paid under current DoD rules, and a higher one still comes through. The real risks are a PCS, a status change, or the end of active service, and you can plan for every one of them before you sign.
As a Military Relocation Specialist in the Cibolo and Schertz corridor, I build that plan with military families, lining up the allowance, the lender's view of it, and a payment that still works if your situation changes. When December's rate release comes, you can watch it knowing your current number is protected and walk into your next showing with a budget built to last the whole tour.
Ready to Build a BAH Budget That Works Near JBSA?
I am Anthony Sharp with Sharp Realty Group, a U.S. Air Force veteran who helps service members buy and sell across San Antonio, Schertz, Cibolo, Universal City, and the wider JBSA corridor. Whether you want a second set of eyes on your allowance, your timeline, or a lender's numbers, let's talk.
Call or text: 210-997-0763
Schedule a time: book a consultation
Email: anthony@sharprealtygrouptx.com
Office: 213 Terramar, Cibolo, TX 78108
Frequently Asked Questions (FAQs)
Does BAH go down if San Antonio rates drop?
Not for a service member who keeps the same BAH status. Under DoD's rate protection rules as written today, you receive the higher of the new January 1 rate or the amount you were paid on December 31.
A newly arriving service member, however, starts on the current published table, which is why San Antonio's lower 2026 rates affected incoming families but not those already here. Your finance office can confirm your own status.
Does BAH rate protection transfer when you PCS?
No. As the rules stand, protection ends with a PCS, and your allowance at the new duty station starts at that area's current published rate. Once you report, the new amount is protected the same way, rising with any published increase and holding steady through any cut, as long as your status stays the same.
Will my BAH change if I buy in Schertz instead of San Antonio?
No. As DoD sets it today, BAH is based on your duty station, pay grade, and dependency status, not your home address. Every JBSA installation shares the same San Antonio housing area under today's DoD boundaries, so a home in Schertz, Cibolo, Converse, or Universal City carries the same allowance as one inside San Antonio city limits.
Can a lender use rate-protected BAH to qualify me for a VA loan?
Often, yes. Lenders generally verify BAH from your LES and may count it as qualifying income when your service is expected to continue after closing. Requirements differ, so ask your loan officer which BAH figure they will use.
I keep a short list of lenders who regularly close VA loans near JBSA and can make an introduction when it helps.
When will 2027 BAH rates for JBSA come out?
Recent tables have come out in mid-December, and the 2026 rates were released on December 11, 2025, for a January 1, 2026, start. DoD sets the schedule, so the 2027 date could differ. Rate protection keeps a current allowance from dropping if the 2027 San Antonio rate comes in lower.
What happens to BAH rate protection if I get married or divorced?
A change in dependency status ends rate protection, and your allowance moves to the current published rate for your new status. At JBSA, the 2026 table puts the gap between the two rates at about $369 a month for several enlisted grades, so run the payment at both rates before you buy around a status change.
* * *
Disclaimer: This article is general information only and does not consider your individual financial, tax, or legal circumstances. BAH rates, rate protection rules, mortgage rates, lender requirements, and market data change and are provided as a general guide, not a guarantee. Nothing here guarantees financing, approval, appreciation, or resale value. Before making a decision, speak with your finance office and a qualified professional such as a REALTOR®, a licensed lender, a tax professional, or an attorney about your specific situation.
Categories
- All Blogs (275)
- BAH (4)
- For Home Buyers (192)
- For Home Sellers (91)
- For Investors (42)
- For Military Service Members (183)
- For Renters (9)
- JBSA (7)
- Local Events (12)
- Local Real Estate News (40)
- Market Updates (42)
- Military Relocation (41)
- Neighborhood Tours (58)
- PCS Move (108)
- Property Tours (6)
- VA Loans (14)
Recent Posts